Key Takeaways
- Early conversations give older adults a meaningful role in important decisions.
- Legal, medical, financial, and emergency information should be organized in one accessible place.
- Care choices can include support at home, assisted living, memory care, and skilled nursing services.
- Clear family responsibilities can prevent missed tasks and reduce conflict.
- Aging plans should be reviewed after significant health, family, financial, or housing changes.
Table of Contents
- Why Planning Matters
- How to Start the Conversation
- Legal Documents to Review
- Health Care Information to Organize
- Long-Term Care Choices
- Money, Benefits, and Care Costs
- Family Roles and Emergency Planning
- When to Review the Plan
- Common Questions Families Ask
- Final Thoughts
Planning for an aging parent is easier when the family starts before a fall, hospitalization, or sudden change in memory creates urgent decisions. Topics commonly addressed through elder law include decision-making authority, future care, public benefits, and ways to prepare for changing needs. Those looking for professional guidance can explore resources on elder law services.
This checklist is designed to help families organize conversations and information without assuming that one plan will work for everyone. State laws, family circumstances, finances, and health needs vary, so a thoughtful plan should be tailored to the older adult’s own wishes.
Why Planning Matters
When a parent has time to consider options, the family can focus on preferences rather than reacting under pressure. Planning also helps identify who can access medical information, pay necessary bills, communicate with providers, and locate essential records if an emergency occurs.
For example, an adult child may be able to help after a hospital stay but still not know which medications a parent takes, where insurance cards are kept, or whether anyone has authority to handle bank transactions. A written plan can turn uncertainty into a manageable set of next steps.
A broader estate planning discussion can help connect future health and care decisions with documents concerning property, assets, and beneficiaries.
How to Start the Conversation
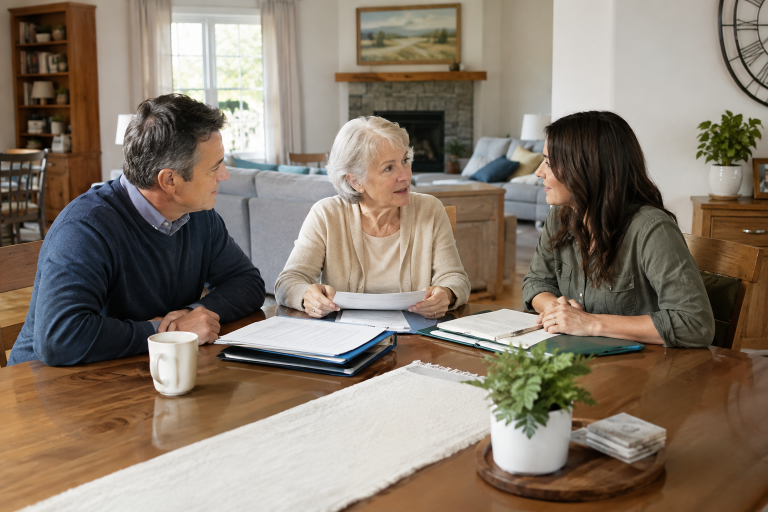
Choose a calm time, avoid treating the discussion as a single all-or-nothing meeting, and center the parent’s preferences. Planning should support independence where possible, not take control away from the person whose life is being discussed.
- What kind of help would make everyday life easier?
- Who should speak for you if you cannot communicate with a doctor?
- Would you prefer to stay at home if you need more assistance?
- Where are your important documents, account details, and emergency contacts?
Legal Documents to Review
Families should locate existing documents and confirm that they reflect current wishes. Requirements and terminology differ by state, so general information cannot replace legal advice for a particular situation.
Financial and Health Care Powers of Attorney
A financial power of attorney may authorize a trusted person to handle specified financial matters. A health care power of attorney, sometimes called a health care proxy, can designate someone to make medical decisions when the patient cannot make or communicate them.
Advance Directives, Wills, Trusts, and Beneficiaries
An advance directive can record care preferences for serious illness. A will directs how property is handled after death, while a trust may be useful in some circumstances. Beneficiary designations on retirement accounts, life insurance, and certain financial accounts also deserve review because they can control how those assets transfer.
Secure Storage
Keep originals and account information secure, but make sure the appropriate trusted people know where to find them. Include the name and contact information of any professionals who retain copies.
Health Care Information to Organize
A current medical summary can make appointments, hospital visits, and care transitions less confusing. Keep it updated after medication changes, new diagnoses, surgery, or rehabilitation.
- Primary care provider, specialists, pharmacy, and emergency contacts
- Medication names, dosages, allergies, and major diagnoses
- Insurance cards, policy information, and recent medical records
- Preferred hospital, treatment preferences, and personal care goals
Long-Term Care Choices
The right setting depends on safety, health needs, finances, location, and personal preference. Aging at home may involve home modifications, meal support, transportation, or paid and unpaid caregiving. Assisted living can provide help with daily routines, while memory care generally offers a more structured setting for people with cognitive impairment. Skilled nursing may be appropriate when regular nursing care or rehabilitation is needed.
Families comparing services should ask about available support, staffing, costs, contract terms, location, visiting policies, and how care needs are reassessed. The federal overview of long-term care coverage explains that Medicare generally does not pay for most non-medical long-term care, which makes advance financial planning important.
Money, Benefits, and Care Costs
Begin with a practical picture of monthly income, regular expenses, insurance, savings, retirement accounts, pensions, property, debts, and likely out-of-pocket costs. Medicare, Medicaid, private long-term care insurance, and veterans’ benefits, when applicable, have different eligibility rules and coverage limits.
Do not make large gifts, transfer property, or change account ownership solely on the basis of general online advice. These choices can have legal, tax, and public-benefit consequences.
Family Roles and Emergency Planning
A simple written responsibility list can reduce duplicated work and misunderstandings. Assign a primary person and a backup for medical appointments, bill monitoring, home maintenance, family updates, and document storage. Discuss travel limits, caregiving availability, financial contributions, and boundaries openly.
For an urgent event, first address immediate safety and call emergency services when necessary. Bring the medication list and insurance information, notify the designated decision-maker, write down discharge instructions, and reassess whether the current home or care arrangement remains safe. Families seeking local services can use the community resources for older adults and families available through the Eldercare Locator.
When to Review the Plan
Review the plan at least annually and after a marriage, divorce, death, move, major diagnosis, health decline, change in finances, new caregiver role, or move into a care community. Update contact details, authorities, and preferences whenever circumstances change.
Common Questions Families Ask
When should planning begin?
The best time is before help is urgently needed, when the older adult can participate fully and explain what matters most.
Does an adult child automatically have authority?
Not necessarily. Authority to make financial or medical decisions depends on applicable law, valid documents, and the facts of the situation.
What if no power of attorney exists?
If a person loses capacity without appropriate documents, court involvement may be necessary. Local legal guidance can help families understand the available options.
Final Thoughts
A family aging plan is a living record, not a one-time task. By taking small, organized steps in 2026, families can better honor a parent’s values, prepare for changing care needs, and make difficult moments less confusing.

Leave a Reply